
Accounting Software for Small Businesses Explained
Can accounting software make bookkeeping easier, prepare your tax return and reduce accountancy fees? We explain what to expect and how Craigerne Accountancy can help.
7 MIN READ | BOOKKEEPING & SOFTWARE
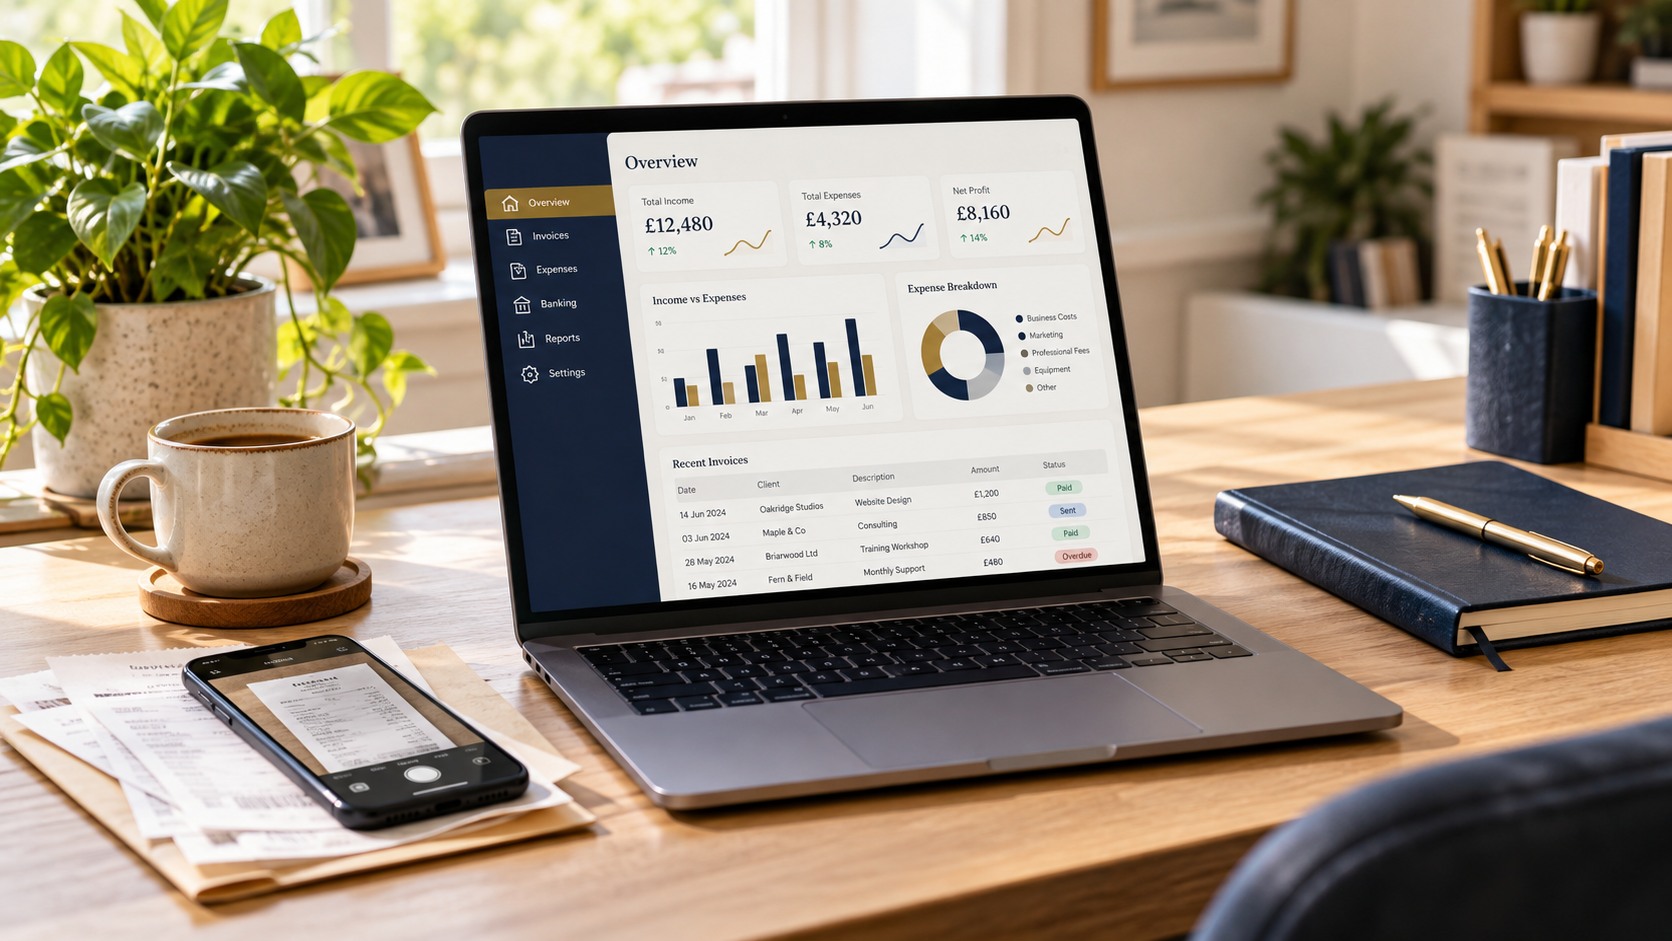
Accounting software can make it easier to keep on top of your business finances. It can reduce paperwork, save repeated typing and help you see what you are earning, spending and owed.
But how much does it actually do? Can it prepare your accounts and tax return? And will you still need an accountant?
This guide explains what to expect, what to check before subscribing and how Craigerne Accountancy can help you get started.
What can accounting software do
Most cloud accounting packages let you work through a web browser, with a mobile app for certain everyday tasks. Depending on the package and subscription, useful features include:
Bank feeds: import transactions from supported bank accounts.
Invoices: create and send invoices, track unpaid amounts and send reminders.
Receipts and expenses: upload documents or photograph receipts, with some tools extracting the details.
Bookkeeping: organise income and spending into categories and match payments to invoices.
Reports: show business income, costs and profit, plus money customers owe you.
Tax tools: help with estimates, VAT or other submissions where supported.
These features can reduce the amount of information you enter more than once. Availability, limits and extra charges vary, so check the specific plan.
Is it easy to use
You do not need to become an accountant to handle the everyday tasks. The aim is to learn a few useful routines: sending an invoice, uploading a receipt and checking what a bank transaction relates to.
There is still a learning curve, particularly at the start. Correct opening figures, sensible categories and the right settings make a difference.
At Craigerne Accountancy, we can help you set up your software and show you how to use the features relevant to your business. You can start with the basics and build confidence as you go.
Does it really make bookkeeping easier
It can, especially if you currently type transactions into a spreadsheet or sort through receipts at the end of the year.
For example, you might photograph a supplier receipt when you buy something, then match it to the payment when it appears through the bank feed. Keeping the document and transaction together makes them easier to find later.
However, imported transactions and suggested categories still need checking. A loan paid into your bank account should not be treated as sales income, and personal spending should not simply be recorded as a business expense.
Software reduces repetitive work, but the records still need to reflect what actually happened. A short, regular bookkeeping routine helps prevent a backlog.
Can it prepare my accounts and do the filings
Some packages can handle parts of this process, but bookkeeping, preparing annual accounts and filing tax returns are different functions.
Software can turn your bookkeeping records into reports showing income, expenses and profit. Those records provide the starting point for preparing your annual accounts and tax returns, reducing the need to enter the same information again.
Depending on the product and the features you subscribe to, it may also support submitting VAT returns, personal tax returns or company accounts and Corporation Tax returns to HMRC and Companies House. Some functions are built in, while others need an add-on or your accountant’s professional software. We can help you establish what is included and what additional support you need.
The key is to distinguish a report generated from your records from a completed set of accounts or a return that is ready to file. Missing transactions, the treatment of equipment purchases and expenses that are not allowable for tax can all affect the final figures.
Before filing, someone still needs to check that the records are complete and that any necessary accounting and tax adjustments have been made. At Craigerne Accountancy, we can agree who handles the bookkeeping, who reviews the figures and who prepares and submits each return.
Does it link to my Self Assessment
It can, but check exactly what the product supports.
It can help connect the two. Your bookkeeping records provide the business income and expense figures needed for your tax return, reducing repeated data entry. The exact process depends on whether you are within Making Tax Digital and which software you use.
Some filing tools are designed for accountants, while others can be used directly by business owners. Buying a bookkeeping subscription does not necessarily give you everything needed to complete your personal tax return. We can explain the appropriate route for your circumstances.
Your business records may only cover part of your tax position. Employment income, savings interest, dividends, property income and other relevant details may also need to be included. A business profit figure on a dashboard is not necessarily your final taxable profit or personal tax bill.
Craigerne Accountancy can help bring the information together and check that the chosen filing route covers your circumstances.
Can software automate Making Tax Digital filings
Yes, some software can automate submissions as well as prepare the figures.
Compatible software can use your bookkeeping records to prepare quarterly updates and support the annual tax submission, reducing manual entry. You or your accountant can manage the filing process through the appropriate software.
Automatic preparation is different from automatic submission. Some providers go further: FreeAgent, for example, can schedule quarterly submissions once configured. This does not extend to its year-end submissions. The available automation depends on the provider and settings.
The process should be agreed in advance: who keeps the records up to date, who checks them, whether approval is required before submission and who checks that HMRC has accepted it. An automated submission can still contain incomplete or incorrectly categorised information.
We can help configure a suitable process and explain which parts your chosen software automates.
If Making Tax Digital for Income Tax applies to you, compatible software is needed to maintain digital records, send quarterly updates and submit your annual tax return. Quarterly updates are summaries of business income and expenses, not separate tax returns.
You may use one suitable product or a combination of compatible tools. Spreadsheets can still play a role when connected through appropriate bridging software. The software must support the income sources and submissions you need. HMRC’s software guidance explains what to check.
We can help you check what applies to you and choose a workable approach. Our Making Tax Digital guide explains the wider requirements.
Could it reduce my accountancy fees
Possibly, if it reduces the work involved. Doing the everyday bookkeeping yourself can reduce the work you need to pay an accountant or bookkeeper to do. Complete, well-organised records can also help avoid additional charges for missing paperwork, correcting entries or reconstructing the books.
That principle applies whoever prepares your accounts. It does not guarantee that every accountant will reduce a fixed fee or include all support at no extra cost.
However, buying software does not automatically reduce your fees. The overall cost also depends on:
How much bookkeeping you do yourself.
The quality and completeness of your records.
The accounts, tax returns and advice you need.
Software subscriptions, setup, training and any ongoing support.
Poorly maintained software records can still take time to put right. The sensible comparison is the combined cost of software and professional support, alongside the time it saves you.
At Craigerne Accountancy, we can discuss the division of work and explain what is included in your fee before you commit.
Can Craigerne Accountancy access the software and help me
Yes. With your permission, Craigerne Accountancy can have a separate accountant or administrator login, where supported, with access appropriate to the work you have agreed.
A practical arrangement is for you to handle the core day-to-day work: raise invoices, upload receipts and check incoming bank transactions. Craigerne Accountancy can help you learn the process, resolve queries and review the records at agreed intervals.
Because you work from the same records, Craigerne Accountancy can look at the transaction you are asking about and help put it right. The aim is to build your confidence and maintain cleaner books throughout the year, reducing the amount of sorting out needed later.
You should use the software’s invitation and permissions settings rather than share your personal password. Software access and authorisation to act for you with HMRC are separate arrangements.
Access also does not mean someone is continuously monitoring your records. We would agree how often reviews take place and which tasks each of us will handle.
Which software providers are available and how much do they cost
Xero, FreeAgent, QuickBooks and Sage are among the options available, alongside other accounting packages and specialist tools. There is no single best choice for every business.
Many packages charge a monthly or annual subscription, with the cost depending on the features, number of users and level of functionality. Some providers offer free or lower-cost options for simpler needs, and software may sometimes be included with a qualifying business bank account.
Look beyond an introductory discount and consider the ongoing cost, VAT and any extras for payroll, receipt processing or tax filing. A lower-priced plan may be enough for a straightforward business, while more complex requirements can justify a fuller package.
Craigerne Accountancy can help you compare suitable providers and choose a package that fits your business, budget and confidence with technology. If you already use software, we can first discuss whether it meets your needs before recommending a change.
We can help you choose suitable software or make better use of the package you already have. Our advice is guided by what suits your business.
How do I choose the right package
Start with what your business needs. Consider your business structure, transaction volume, invoicing, VAT, payroll, stock and any other systems you use. Check that the software supports your bank and the filing requirements relevant to you.
Compare the ongoing subscription price as well as any introductory discount. Ask whether receipt processing, extra users, payroll, tax filings or other features cost more.
A trial can help you judge whether the everyday tasks feel manageable. It is also worth checking how you can export your records if you later change provider.
We can help you assess suitable options before you subscribe, so you pay for the features you need.
Can I keep using spreadsheets or switch from another system
The right approach depends on your reporting obligations and how you prefer to work. A simple spreadsheet may still suit some businesses, although applicable digital filing rules must be met.
If you are moving to new software, you do not necessarily need to re-enter every historic transaction. The amount to transfer depends on the changeover date, reporting needs and what the new system can import. Opening balances, unpaid invoices and outstanding bills need particular care.
We can help plan the changeover and check the starting figures, while making sure the records you need remain accessible.
How Craigerne Accountancy can help
At Craigerne Accountancy, we combine software certification with strong practical experience across a range of accounting packages. We can help you choose a suitable system, get set up and confidently manage your day-to-day bookkeeping.
We support small businesses in Peebles and the Scottish Borders, whether you are starting from scratch or looking to improve your existing bookkeeping routine.
Our aim is to get you comfortable with the everyday tasks, with professional support available where you need it. You remain involved in your finances while giving your accountant clearer, better-organised records.
Depending on the support you need, we can:
Help you choose a suitable package and subscription.
Set up your business details, opening figures and bookkeeping categories.
Help connect supported bank feeds and establish receipt and invoicing routines.
Show you how to handle the everyday tasks.
Use agreed accountant access to answer questions and help resolve problems.
Review your records and prepare accounts and tax submissions within your agreed service.
You may want to do most of the bookkeeping yourself, share the work with us or ask for more ongoing support. We can discuss an arrangement that suits your business and confidence with technology.
Thinking about accounting software, or already paying for a package you are struggling to use? Get in touch with Craigerne Accountancy to discuss your options and request a free quote.
Sole Trader or Limited Company – Which Is Right for Your Business ?
Should you operate as a sole trader or limited company? We explain the key tax, pension and practical differences — and why the right choice depends on your profits, personal income needs and future plans.
6 MIN READ | BUSINESS & TAX
One of the most common questions small business owners ask is:
The fundamental difference
But doesn't a limited company mean paying tax twice?
What choices does a company give you?
Salary – providing personal income, potentially subject to Income Tax and National Insurance.
Dividends – distributing post-Corporation-Tax profits, potentially subject to dividend tax but not National Insurance.
Pension contributions – the company can potentially make employer contributions directly into a director's pension.
Retaining profits – money not currently required personally may remain within the company.
Why can a company become more attractive as profits grow?
Can retaining profits help with future tax planning?
What about pensions?
What are the downsides of a limited company?
So, which is right for you?
The key takeaway
Let us run the numbers for you
Pensions for Small Business Owners: Limited Company vs Sole Trader
Should your business pay into your pension? This practical guide explains how pensions work for limited company directors and sole traders, the tax benefits, contribution limits and upcoming inheritance tax changes.
6 MIN READ | BUSINESS & TAX
Pensions for Small Business Owners: A Practical Tax Guide
For small business owners, pensions aren't just about saving for retirement. They can also be one of the most tax-efficient ways of using business profits to build long-term personal wealth.
But how pension contributions work — and the tax relief available — depends significantly on whether you run a limited company or operate as a sole trader.
In this guide, we answer some of the most common questions business owners have about pensions and explain where a little forward tax planning can make a real difference.
Why are pensions so tax-efficient?
Pensions benefit from several important tax advantages.
Depending on how contributions are made, you or your business may receive tax relief when money goes into the pension.
Once invested, money within a pension can generally grow without UK Income Tax or Capital Gains Tax being charged on investment returns.
The trade-off is that pension savings are designed for retirement, so you normally can't access the money until you reach the minimum pension age. Tax may also be payable when pension money is eventually withdrawn.
For business owners there is another important consideration:
How you put money into your pension can be just as important as how much you contribute.
I'm a limited company director. Should my company pay into my pension?
For many owner-directors, making an employer pension contribution directly from the company is an attractive option.
Rather than taking money out of the company personally and then contributing it to a pension, the company makes the pension contribution directly.
This can have two important tax advantages.
1. You don't need to extract the money personally first
If profits are extracted from a company as additional salary or dividends, personal tax and potentially National Insurance can arise.
A direct employer pension contribution avoids the need to extract that money personally before putting it into a pension.
2. The company can potentially receive Corporation Tax relief
Provided the pension contribution meets the relevant tax rules, including being incurred wholly and exclusively for the purposes of the company's trade, it will normally be deductible when calculating the company's taxable profits.
That can reduce the company's Corporation Tax bill.
For an owner-director who has accumulated surplus cash within a profitable company and wants to build their pension, this can therefore be a particularly tax-efficient route.
Can my company contribute more than my salary?
Potentially, yes.
This is an important point for many small company owners.
Owner-directors often take a combination of a relatively modest salary and dividends.
If you personally make a pension contribution, the amount on which you can receive tax relief is generally linked to your relevant UK earnings. Dividends aren't relevant earnings for this purpose.
Employer pension contributions work differently.
Your company can potentially make a pension contribution greater than your salary because employer contributions aren't subject to the same relevant-earnings restriction.
For example, a director receiving a relatively modest salary could potentially have their company make a substantially larger employer pension contribution.
The pension annual allowance and other pension rules still need to be considered.
This is one reason company pension contributions can be particularly useful for owner-managed businesses.
How much can my company pay into my pension?
The standard pension annual allowance is currently £60,000 per tax year.
The allowance looks at the total amount going into your pensions, including employer contributions.
However, £60,000 isn't necessarily an absolute ceiling.
You may be able to use unused annual allowance from the previous three tax years under the carry forward rules.
This can be particularly valuable for business owners.
Imagine you've concentrated on growing your business for several years and made relatively modest pension contributions. The business then has an especially profitable year and accumulates surplus cash.
Depending on your previous pension contributions and circumstances, carry forward could potentially allow the company to make a pension contribution significantly above the normal £60,000 annual allowance.
Different rules can apply to some higher earners and to people who have already flexibly accessed pension benefits, so available allowance should be checked before making a large contribution.
When should a limited company make the pension contribution?
Timing can matter.
Employer pension contributions are normally relieved for Corporation Tax purposes when they are actually paid, rather than simply when the company decides that it intends to make the contribution.
That makes pension planning particularly relevant before your company's financial year-end.
For example, if your company has had a profitable year and has surplus cash, you might consider:
How much cash does the business need?
How much do I need to extract personally?
Would I like to put more towards retirement?
Does the company have scope to make an employer pension contribution before year-end?
Looking at these questions together can be much more useful than considering the pension after the company's accounts have already been prepared.
I'm a sole trader. Does it work differently?
Yes.
A sole trader and their business aren't separate legal entities in the same way as a limited company and its owner.
You therefore don't have a company making an employer contribution for you.
Instead, a sole trader will normally make personal pension contributions.
Many personal pensions and SIPPs operate using a system called relief at source.
Suppose you want £10,000 invested into your pension.
You normally pay:
£8,000
Your pension provider claims:
£2,000 from HMRC
And the amount invested in your pension becomes:
£10,000
You don't normally have to contact HMRC to obtain that basic-rate relief — the pension provider claims it.
If you're entitled to additional tax relief because you pay tax at a higher rate, further relief may be available. Depending on your circumstances, this may need to be claimed from HMRC, including through your Self Assessment tax return.
How much can a sole trader contribute?
For personal contributions, tax relief is generally available on gross pension contributions up to 100% of your relevant UK earnings, subject to the pension rules and annual allowance.
For a sole trader, profits from the trade can therefore be important in determining the amount of tax-relieved personal contributions that can be made.
This creates another useful year-end planning opportunity.
If you've had a particularly profitable year, making a pension contribution could potentially both increase your retirement savings and improve your personal tax position.
Can I pay into a pension if my income is very low?
Yes, although the amount receiving tax relief can be restricted.
Even someone with little or no relevant UK earnings can normally make a £2,880 net contribution to a relief-at-source pension.
The pension provider can then claim £720 basic-rate tax relief from HMRC, resulting in:
£3,600 being invested in the pension.
This can be useful for people taking a break from work, working relatively few hours or earning only a small amount from their business.
Is a pension better than an ISA?
Not necessarily. They do different jobs.
With an ISA, you contribute money that has already been taxed. There is no tax relief when the money goes in, but investments can grow free of UK Income Tax and Capital Gains Tax and withdrawals are generally tax-free.
With a pension, there can be valuable tax relief when money is contributed, and investments can also grow in a tax-efficient environment.
But pension money is less accessible and some withdrawals may eventually be taxable.
For many business owners, the answer isn't pension or ISA.
It can be useful to have both:
Pension: long-term retirement savings with potentially significant upfront tax advantages.
ISA: tax-efficient investments that remain accessible when you need them.
The appropriate balance depends on your circumstances and financial objectives.
What happens to my pension when I die?
This is an area where the rules are changing.
Historically, pensions have often sat outside an individual's estate for Inheritance Tax purposes.
From 6 April 2027, most unused pension funds and pension death benefits will be brought within an individual's estate for Inheritance Tax purposes.
This doesn't remove the other tax advantages of pensions, but it does change one of the attractions pensions have historically had for estate planning.
For business owners with substantial pensions, property, investments or other assets, pensions should therefore increasingly be considered as part of their wider estate and retirement planning rather than automatically being viewed as outside their estate.
Does my pension affect whether I should be a sole trader or limited company?
Potentially — although pensions should normally be one consideration rather than the reason for choosing a particular business structure.
There are important differences between operating as a sole trader and through a limited company, including how profits are taxed, administrative requirements, legal responsibilities and how money can be taken from the business.
Pensions are another difference worth considering.
As a sole trader, pension contributions are normally made personally and the amount qualifying for tax relief is linked to your relevant UK earnings.
With a limited company, the company can potentially make employer pension contributions directly for a director. These aren't subject to the same relevant-earnings restriction and may also be deductible when calculating the company's taxable profits.
For someone intending to make substantial pension contributions over a number of years, this may therefore form part of the wider sole trader versus limited company calculation.
It shouldn't be considered in isolation. The right business structure depends on your profits, how much money you need personally, future plans and wider tax and commercial circumstances.
Related guide: Sole Trader vs Limited Company – Which Is Right for Your Business?
Pension or leave the money in my company?
This is often the more interesting question for an established business owner.
If your company has accumulated surplus cash, there are several possible uses for it.
You might:
retain the cash within the company;
reinvest it in the business;
extract some for personal spending or investment; or
contribute some to your pension.
A pension contribution can be extremely tax-efficient, but it also moves the money from an accessible company asset into a pension that you may not be able to access for many years.
The decision therefore isn't purely about achieving the lowest possible tax bill.
It should also consider the company's future cash requirements, your personal cash requirements and your longer-term plans.
When should a business owner review their pension?
Pension planning can be particularly worthwhile:
when deciding whether to operate as a sole trader or limited company;
before your company's financial year-end;
after an especially profitable year;
when cash is accumulating within your company;
when reviewing your salary and dividends;
when your income moves into a higher tax band;
if you haven't made significant pension contributions for several years;
when approaching retirement; or
when reviewing your wider estate and Inheritance Tax position.
The important point is that pension planning shouldn't sit completely separately from your business and tax planning.
How can Craigerne Accountancy help?
Pension planning for a business owner doesn't start with choosing a pension fund. There are often important business and tax decisions to make first.
At Craigerne Accountancy, we can help you consider pensions as part of your wider business and personal tax planning.
Choosing how to structure your business
If you're starting a business — or considering moving from sole trader to limited company — we can help you understand the financial and tax implications of the different structures.
Pensions can form part of that analysis.
We can look at your expected profits, how much income you need personally, your plans for the business and your pension objectives when considering whether operating as a sole trader or limited company may be appropriate.
Read our related guide: Sole Trader vs Limited Company – Which Is Right for Your Business?
For limited company owners
We can help you:
assess whether the company should make employer pension contributions;
estimate the Corporation Tax effect of a contribution;
consider pension contributions alongside salary and dividends;
look at the timing of contributions around your company's year-end;
consider the company's available profits and cash; and
understand the tax implications before money is extracted from the company.
For sole traders
We can help you:
understand how pension contributions affect your tax position;
identify whether additional pension tax relief may be available;
incorporate pension contributions into your Self Assessment tax planning; and
consider the effect of contributions when profits are particularly high.
Your accountant's role is different from that of a financial adviser. We can help with the business, accounting and tax implications of making pension contributions.
Where you need advice about which pension or investments to choose, or other regulated financial advice, we can work alongside your financial adviser.
Thinking about making a pension contribution?
If you're starting a business, reviewing its structure or considering putting a significant amount into your pension, it's worth looking at the tax position before making the decision.
Speak to Craigerne Accountancy and we can help you understand how pensions fit into the wider tax picture for you and your business.
This article provides general information about the tax treatment of pension contributions and is not personalised tax, pension or financial advice, nor a personal recommendation. Craigerne Accountancy does not advise on the suitability of particular pension products, pension providers, investments or investment strategies. Pension and tax rules depend on individual circumstances and may change over time. Where regulated financial advice is required, we recommend that you speak to an appropriately authorised financial adviser.